In residential construction, profit margins are often won or lost in the details nobody talks about during the sales process. While material pricing and labor rates usually dominate budgeting conversations, experienced builders know the real financial threats tend to emerge in the “hidden” categories — the overlooked expenses that quietly erode margins, delay schedules, and strain client relationships.
For professional home builders operating in today’s market, understanding and proactively managing these hidden costs is essential not only for profitability, but also for maintaining reputation, client trust, and operational stability.
Modern residential construction faces a unique combination of pressures, notably including volatile material pricing, ongoing labor shortages, longer lead times, increasing code complexity, rising insurance and financing costs, and more demanding homeowner expectations. A project that appears profitable on paper can quickly become marginal once indirect and unplanned costs begin accumulating. Builders who consistently succeed are typically the ones who account for uncertainty before construction begins.
Design Revisions and Scope Creep: Clients often continue refining floor plans, finishes, and structural options well into the planning phase. Every revision may require additional architectural coordination, engineering updates, permit resubmissions, repricing of materials and labor, and adjusted scheduling. Even small modifications can create cascading administrative costs that are rarely visible to homeowners.
Site Evaluation and Engineering: Raw land frequently introduces surprises that can include poor soil conditions, drainage complications, rock excavation, tree removal, environmental mitigation requirements, and utility access limitations. Without detailed geotechnical analysis early in the process, builders may inherit significant unforeseen site-development expenses.
- Permit Delays and Municipal Requirements. Permitting timelines have become increasingly unpredictable in many jurisdictions. Hidden costs associated with permitting often include:
- Idle labor scheduling
- Equipment downtime
- Extended financing carry costs
- Delayed subcontractor availability
- Re-inspection fees
- Additional documentation requests
Municipalities are also enforcing stricter energy-efficiency, stormwater, and zoning compliance requirements, creating additional consulting and revision expenses. Builders who fail to build adequate time contingencies into schedules often absorb these costs directly.
- Material Price Volatility. While most builders anticipate fluctuations in lumber pricing, volatility now affects nearly every construction category from electrical components, HVAC equipment, concrete products, windows and doors to plumbing fixtures and roofing materials. Long lead times further complicate budgeting because quoted prices may expire before installation occurs.
- The Margin Compression Problem. Fixed-price contracts can become especially risky during volatile markets. Builders may secure a project based on current pricing only to discover major increases weeks later when materials are finally ordered. Protection can be sought through measures like escalation clauses, allowance structures, early procurement strategies, and supplier relationship agreements. Without these protections, material inflation can quietly eliminate expected profits.
- Overtime premiums
- Schedule compression expenses
- Rework from inexperienced crews
- Productivity decline due to understaffing
- Increased project management oversight
- Delays caused by subcontractor overbooking
In many regions, reliable subcontractor availability has become one of the most valuable assets a builder can maintain.
- Client-Driven Change Orders. Change orders are one of the most common — and underestimated — sources of hidden cost. Even when builders charge for modifications, the true impact often extends beyond the direct change itself. A single late-stage client revision may trigger material reorder fees, lost labor efficiency, demolition and rework, schedule disruptions, trade coordination conflicts, and inspection rescheduling. The administrative burden alone can become substantial on highly customized homes.
If you manage expectations early, it can be a game-changer. Builders who invest heavily in pre-construction communication often experience fewer costly mid-project changes. Detailed selections, transparent allowances, and documented approvals can significantly reduce downstream friction.
- Warranty and Post-Completion Expenses. The project is not financially complete when the homeowner moves in. Post-construction costs frequently include:
- Warranty callbacks
- Minor cosmetic repairs
- Appliance coordination
- Punch-list labor
- Seasonal adjustments
- Customer service administration
These costs are often under-budgeted despite directly affecting long-term client satisfaction and referral business. Builders with weak closeout processes may spend months absorbing unpaid follow-up work.
- Insurance, Financing, and Carrying Costs. Many indirect expenses continue accumulating throughout construction:
- Builder’s risk insurance
- General liability coverage
- Workers’ compensation
- Interest on construction loans
- Equipment rental extensions
- Temporary utilities
- Security measures
Longer project timelines magnify all of these categories simultaneously. Even weather delays can create significant carrying-cost exposure when schedules are already tight.
- Technology and Administrative Overhead. Modern residential construction requires significantly more operational infrastructure than in previous decades. Today’s builders often absorb costs related to:
- Project management software
- Estimating platforms
- CRM systems
- Drone surveying
- Digital plan management
- Cybersecurity
- Accounting integration
- Compliance tracking
While these tools improve efficiency, they also add ongoing overhead that must be reflected in pricing structures.
- Energy Code Compliance and Sustainability Requirements. Energy efficiency expectations continue rising across the industry. Builders now face growing costs associated with advanced insulation systems, air sealing verification, energy testing, higher-efficiency HVAC systems, smart home integration, and solar readiness requirements. These upgrades may improve long-term homeowner value, but they also increase upfront construction complexity and coordination.
- Reputation Costs: The Most Overlooked Expense. Perhaps the largest hidden cost is reputational damage caused by poor communication, missed timelines, or unexpected pricing disputes. In an industry driven heavily by referrals and online reviews, a single poorly managed project can affect future revenue opportunities for years. Professional builders increasingly recognize that transparency itself is a financial strategy. When clients understand realistic timelines, contingency planning, material volatility, and change-order implications, they are far more likely to remain cooperative when challenges emerge.
Strategies to Protect Margins
Reduce hidden-cost exposure by implementing disciplined operational systems:
Build Larger Contingencies Into Budgets - Contingency allowances should reflect current market volatility, not historical norms.
Strengthen Pre-Construction Processes - Investing more time before breaking ground often prevents expensive downstream corrections.
Use Detailed Scope Documentation - Clear specifications reduce ambiguity for both clients and subcontractors.
Vet Subcontractors Carefully - Reliable trade partners reduce delays, rework, and supervision costs.
Communicate Constantly With Clients - Transparent communication minimizes surprises and helps preserve trust during inevitable project changes.
Track Cost Data Aggressively - Builders who monitor historical job-cost data are better positioned to estimate future projects accurately.
Hidden costs are no longer occasional disruptions in residential construction — they are a permanent part of the business environment. The builders who remain consistently profitable are not necessarily the ones with the lowest bids or fastest schedules. They are the ones who understand the full financial ecosystem of a project and prepare for uncertainty before it appears. For professional home builders, profitability today depends less on avoiding hidden costs entirely and more on anticipating, managing, and communicating them effectively. In a market defined by complexity, operational discipline has become one of the industry’s greatest competitive advantages.
A few weeks ago, a builder called to get a general liability quote. I asked when his current policy expires. He replied, “oh, I let that policy go a few months ago when my last project was finished.” Are you no longer in business? I asked. “Sure,” he said, “I just don’t need insurance since I’m not building right now.”
I was beginning to feel a little uncomfortable. Did you sell your last house then? was my next question. “No,” he innocently replied. Are you trying to sell it? I asked. “Of course, I’ve got open houses every weekend. I had maybe two dozen people walk through just last Sunday,” he said with pride.
As our conversation continued, it slowly emerged that this builder simply didn’t think he had any responsibility to the public during his weekend open house tours. Not only that, but he had also recently gone back to an earlier home buyer to finish a downstairs family room. Yet another past customer had asked about adding a Florida room. Our builder gave an estimate and was waiting to hear back. He admitted he’d “probably” need general liability insurance then to do these small projects, but it was clear he didn’t really see the risks involved. Whether this was due to a desire to control costs, an over-reliance on his subcontractors, or just a lack of understanding as to how general liability insurance works, is hard to say. To this builder’s credit, he allowed me the time to walk through the liability risk potential of each scenario we discussed.*
 First, the weekend open house tours: Until it is sold, the home, finished or not, is the property of the builder and he is liable for bodily injury to any member of the public who sets foot on any part of the property and is injured. This is true whether they are there as invited guests between 1:00 and 4:00 each weekend, or if they stop by unannounced after work on a Tuesday. In fact, if anyone who is not working for the builder gets hurt while on the property, they have a right to file a liability claim and a lawsuit against the builder. Without general liability insurance, the builder is on his own.
Next, finishing the family room: The subcontractor hired to do this small job has his own general liability insurance and the builder has a certificate proving it, issued when the policy renewed about four months ago. Unfortunately, the sub’s policy was recently cancelled for non-payment of premium. While at the home, the subcontractor carelessly drops a cigarette butt that starts a fire causing over $100,000 in damage to the home. The smoke, heat and water damage sustained by the home next door when the fire department put out the blaze isn’t covered either. That’s worth another $215,000. All this damage would have been insured in addition to the cost to defend the builder in the resulting lawsuits, had our builder not canceled his general liability policy when he finished construction.
 Last, but not least, the Florida room: The subcontractor has active general liability insurance. Nothing happens during the project. Everyone’s happy. Then, about a year later, during an unusually cold winter, the homeowner starts his gas fireplace for the first time in ages. The fireplace is in the living room that adjoins the new Florida room. Not long after flipping the switch, there is a terrible explosion. The house is a total loss. It seems the subcontractor had nicked a gas line with a drill during installation of the prefab Florida room. With such a catastrophic loss, the subcontractor’s policy limit is quickly used up. Our builder’s policy would have provided excess limits because the builder is liable for hiring the subcontractor who nicked the gas line. Since our builder doesn’t have $1,000,000 laying around, he’d lose his business in this scenario.
So, what are the odds of any of those things actually happening? It's anybody's guess. You see, insurance is based on the law of large numbers. If you toss a coin enough times it will come up heads half the time. If you toss it only a few times, there’s little chance of predicting heads or tails. Are you feeling lucky?
*These are only a very few of the potential risks associated with general liability and are intended merely to illustrate the potential for uninsured losses.
Good news -- we gotcha covered! Contact us today for more info on GL, Builders Risk, or Contractor's Equipment Insurance. The RWC Insurance Advantage (RIA) program is offered exclusively to our builder members. Because of that, we are able to avoid the high risks associated with other commercial operations. Thus, we keep the cost of claims low and pass the savings on to you. More info / questions: 866-454-2156 or info@rwcinsuranceadvantage.com.
www.rwcinsuranceadvantage.com
By Doug Davis, RWC Insurance Advantage
 If you’ve been a builder for more than a few years you’ve been through a lot. When the housing bubble burst; you survived. Now that the market is better and your business is growing, you’re starting to realize the rewards of surviving. There are still plenty of challenges and one of them is to find qualified subcontractors.
Recently, you started a new subdivision and hired a flat concrete contractor you’ve never worked with before, to put in the sidewalks. This morning you got a call from your new sub; the kind you never want to get. A woman was walking her dog next to your project around dusk last night. She tripped over a mason’s line that was left across a section of sidewalk that had been poured earlier that day. The new flat work guy left the site without setting up any cones, fencing or signs. In fact, he did nothing to warn the public of what is commonly referred to as a “trip & fall hazard.” The woman suffered fractures to both wrists as well as lacerations to her face when she fell. Her injuries will require surgery and she’ll be unable to work for several months. Her pain and suffering have yet to be determined.
Your new sub has his own general liability insurance that should respond to this claim. You required him to have his insurance company add you to his policy as additional insured. That way they will defend you if and when the woman’s attorney sues you as well as your sub. The certificate of insurance you required your sub to provide shows all of this. Everything should be fine. But, trip & fall claims can spiral out of control.
Disputes can arise over who should have protected the worksite. Subcontractors or, their attorneys, can argue that’s the general contractor’s job. You feel that you don’t have time to hover over every job site making sure each sub is placing the proper emphasis on safety. Besides, you hired them to do a job and that includes doing it safely. Doesn’t it? All your subs understand this, don’t they?
In most states, you as the general contractor, are ultimately responsible for worksite safety. That doesn’t mean the subs get a free pass. But it usually means the general contractor has to do more than just assume everyone is being safe. That means holding periodic safety meetings, making sure new subs understand what you expect from them before starting work each morning, during the workday and after shutting down for the night. Active worksites are dangerous places even when they are nothing more than a partially completed sidewalk in poor light where an unsuspecting woman takes her dog for a walk.
Holding regular safety meetings doesn’t have to take a lot of time or cost you much money. Meetings don’t have to be held every day; just regularly enough to make it clear to everyone concerned that you are committed to preventing accidents involving both the public and anyone else at your worksites.
The RWC Insurance Advantage is dedicated to loss prevention. To prove it, we offer up to 25% off your new general liability premium if you provide us with a copy of your written safety program. If you’re already insured with us, we’ll even offer the same incentive on your next renewal if you haven’t already received it.
Call us today at 866-454-2155 to find out if you qualify and receive a free, no obligation quote.
Today’s home buyers are tech-savvy shoppers who routinely turn to the internet when searching for new homes. As a successful builder, you understand the vital importance of maintaining a solid presence on the internet so potential buyers can find you, learn about what you offer, and discover what makes you better than “the other guys”.
 RWC has an entire section of our website dedicated to educating the homebuyer on everything from how to choose a home builder to understanding what a new home warranty is all about. The following resources can help explain the value of your decision to provide an RWC warranty on your home:
- The Value of an RWC Warranty to Your Home Buyer
- What Your RWC Membership Means to Your Buyer
- Tips on Choosing a Builder (of course being an RWC Member factors in there)
- What’s the Difference Between a Structural Warranty and an Appliance Warranty
- Important Warranty Terms to Know and Understand
Something ‘extra’ you provide which sets you apart from the competition is the fact you offer a 3rd party insured warranty – and not just any warranty – but the RWC warranty. The sales process is complex with a variety of topics to discuss with potential home buyers. Our goal is to make the warranty explanation easier for you by expanding our online resources for your homebuyers. Hopefully, this section will become your “go to” resource for warranty information for your staff and your buyers.
Obviously, it makes perfect sense to provide your buyers with information about your warranty. Simply link your site to the RWC Homeowner section to point them in the right direction and we’ll tell the story for you! We suggest linking to www.rwcwarranty.com/homeowners as your starting point. Your buyers will learn about the extra mile you travel to demonstrate your professionalism and customer service by providing them with this written RWC warranty.
 Did you know that as a member of RWC or HOME of Texas you may be eligible for our General Liability Insurance Program through RWC Insurance Advantage? If you would like to learn how we might meet your general liability coverage needs, call RWC Insurance Advantage today at 866-454-2155 or click here to get a quote. Plus, be sure to read on for some helpful hints about certificates of insurance, subs and staying on top of policies.
Insurance agents hear it all the time; are certificates really that important? If my subs’ certificates aren’t current, am I on the hook for what their policies don’t cover? What about exclusions on my policy? Maybe a hypothetical claim will help provide some answers. Let’s say you contract with a roofer. He’s not the roofer you usually work with but, he has a good reputation and he gives you a certificate of insurance that shows he has his own General Liability policy. It has the same limits as your policy with the RWC Insurance Advantage program. No worries here. His policy will respond first to injuries or damage to others that he might cause while working on your behalf. However, you also notice his Workers Comp is due to renew in about a week but, he assures you the renewal is going to happen and he’ll provide you with an updated certificate just as soon as he gets it from his agent. You need to get your latest project under roof as soon as possible because the weather has been uncertain; so, you decide to take a chance. Besides, it shouldn’t take a week to do a roof. What could go wrong?
The weather takes a turn for the worse. By the time the roof is started it’s been over a week. Then you get the news one of the roofer’s employees has been injured. He didn’t fall but, he hurt his back. Only then do you remember the promised certificate hasn’t appeared. Then your roofer admits his policy was not renewed because he failed to make a payment. Your policy doesn’t cover injuries to the employees of subcontractors. That’s because workers compensation insurance is available to them and is designed to cover the medical bills and lost wages of his employees. As it turns out, waiting for a renewal certificate of insurance might have avoided you being held liable for a loss that isn’t covered under your policy.
• Make sure all your subcontractors provide you with up-to-date certificates of insurance.
• Ask them if they have any open or, unreported claims.
• Be aware of what your policy does and does not cover.
Don’t let someone else’s lack of planning become your problem.
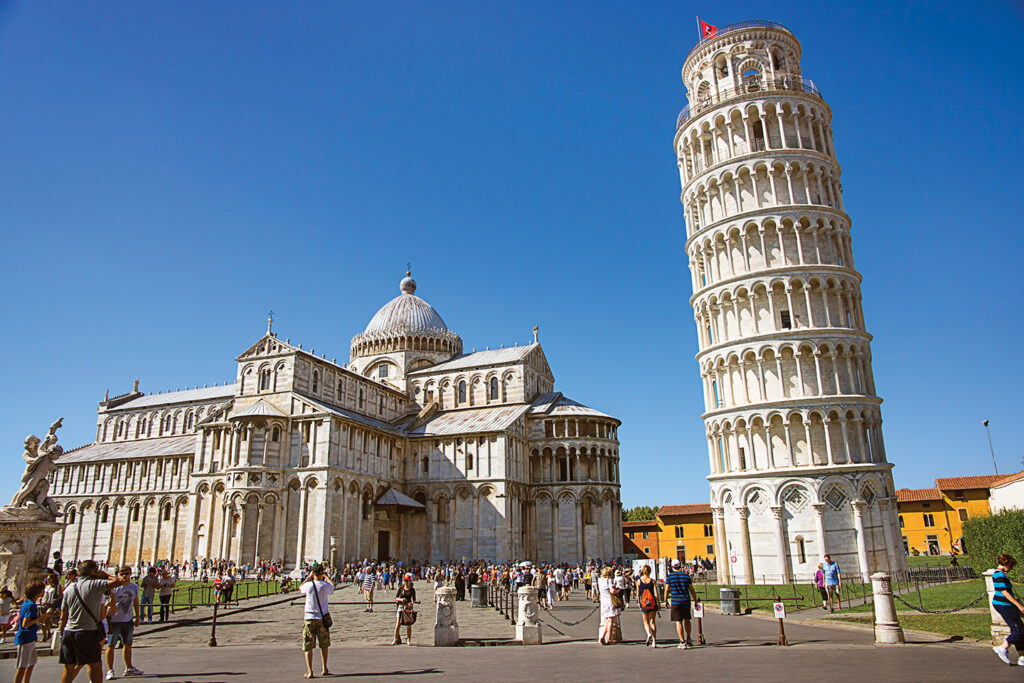 On August 14, 1173 Bonanno Pisano, began construction on an 183’ high marble and stone bell tower in Pisa, Italy. It took nearly 200 years to complete, but trouble started long before. Within five years of breaking ground, the bell tower began to lean due to a shallow foundation set in unstable subsoil. The design was flawed from the beginning. A builder’s worst nightmare? Just the opposite. Today the Leaning Tower of Pisa is one of the world’s most visited tourist destinations.
For the rest of us less able to make lemonade from the occasional lemons we’re handed, we need help. Fortunately, for Pisa, the tower’s lean hasn’t caused it to fall over on all those cash-carrying tourists…yet. If that ever happens, the contractor responsible for maintaining the famous landmark better have general liability insurance. Otherwise, it could become the world’s most famous uninsured construction defect claim. Of course, the tower has been standing for over 600 years without falling, so what else is there to worry about? Each year in this country more than seven million injuries are attributed to “slip and fall” accidents. Imagine how many tourists may have slipped or fallen going up and down the steps of the Leaning Tower of Pisa. Now imagine how many would-be buyers might slip or fall at one of your model homes or active job sites.
Nobody likes thinking about third party liability claims. Bonanno Pisano didn’t have to because he didn’t live to see his project completed. You’re probably planning on being around for a while and I’m guessing those plans don’t include losing everything you’ve worked for because someone was seriously injured at one of your job sites. If my guess is right, we’d like to help. Give RWC Insurance Advantage a chance to review your current general liability coverage. Call us at (866) 454-2155 and ask for Ron Sweigert or click here for a free no obligation quote.